Commercial Food Truck Insurance: Coverage Checklist
Quick answer
A food truck usually needs commercial auto plus liability coverage, with property/equipment and workers' compensation added according to the rig, staffing, contracts, and state rules. Confirm requirements with the relevant agencies, lender, commissary, venues, and a licensed insurance professional before binding coverage.
Commercial food truck insurance is not a single universal policy. Operators usually combine commercial auto, general or product liability, equipment/property coverage, and—when applicable—workers’ compensation. This checklist explains what each coverage does, which requirements can come from law or contracts, and what to confirm before buying. For premiums and monthly budgeting, use the separate food truck insurance cost guide.
What Insurance Does a Food Truck Need?
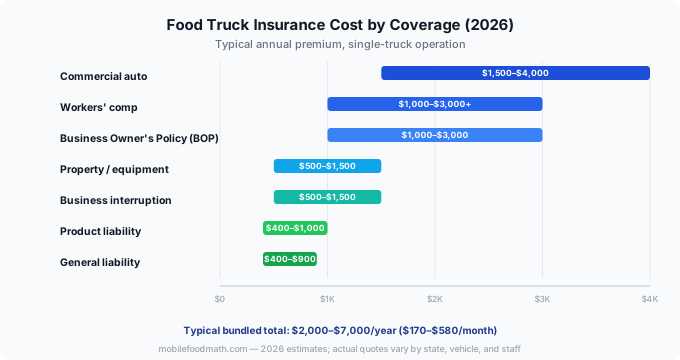
A food truck is several businesses rolled into one vehicle, so it usually needs a stack of coverages rather than a single policy. Most operators carry a combination of the following, often bundled into a Business Owner’s Policy (BOP) or a specialized food-truck program:
- General liability — third-party bodily injury and property damage
- Commercial auto — the truck itself, on the road
- Product liability — illness or injury caused by your food
- Property / equipment / inventory — your gear and stock
- Workers’ compensation — check jurisdiction, staffing and exemptions
- Business interruption — lost income when you can’t operate
Some of these are legally mandated; others are strongly recommended or required by the venues, commissaries, and events you work with. The mix you actually need depends on your state, your staffing, and where you park and serve.
Coverage examples and source limits
Source verification: November 8, 2026. Insureon’s cost page (updated September 18, 2026) reports customer-policy examples of GL $37/month or $440/year, BOP $96/month or $1,147/year, and commercial auto $209/month or $2,509/year. The auto sample includes food-service businesses. These are platform samples, not national averages, NYC quotes or a new operator’s guaranteed prices.
A BOP combines general liability and property coverage; it does not automatically include auto or workers’ compensation. Do not add GL, BOP and auto together as a typical total. GL overlaps with BOP and the examples come from different policy samples. Use the cost guide to compare those named examples, then request quotes for your specified operation.
General Liability Insurance
General liability addresses third-party bodily injury and property damage, subject to policy terms and exclusions. Ask whether food-related product liability is included. FLIP’s advertised starting prices are $25.92/month or $299/year, with listed GL limits of $1 million per occurrence and $2 million aggregate. FLIP explicitly states that this is not a commercial auto policy. These are a named provider’s offer and policy limits, not universal legal requirements or an all-in truck quote.
Commercial Auto Insurance
Commercial auto addresses vehicle liability and any physical-damage coverage you select. Disclose commercial use and ask how permanently installed cooking equipment is treated while driving and parked. Do not assume a personal auto policy covers this use. Insureon’s food-service customer auto example is $209 per month or $2,509 per year; obtain your own quote using the actual vehicle, drivers, garaging location and operation.
Product Liability Insurance
Ask whether the proposed policy covers foodborne-illness and allergic-reaction claims. Product liability may be included in general liability or listed separately. Confirm exclusions and any separate premium before counting the cost twice.
Property, Equipment, and Inventory Coverage
Your griddle, fryer, refrigeration, generator, POS system, and food inventory all represent real money — often tens of thousands of dollars. Commercial property, inland marine and equipment-breakdown policies can cover different losses. Confirm theft, fire, transit, off-site storage and breakdown terms rather than assuming they are interchangeable. Request a quote using documented replacement values. Document your equipment with receipts and photos so claims go smoothly.
Workers’ Compensation Insurance
Check the state workers’ compensation authority for staffing thresholds and exemptions before hiring. Coverage and premiums depend on jurisdiction, payroll, classifications, and policy terms; obtain a quote for the actual staffing plan.
Business Interruption Insurance
Business interruption (sometimes called business income) replaces lost revenue when a covered event — say a fire or major equipment failure — forces you to stop operating while you repair or rebuild. For a seasonal or event-driven business, even a few weeks offline can be financially serious. Ask whether it is included in a BOP or needs a separate endorsement and premium. Note that most policies exclude routine slow seasons and many pandemic-style shutdowns, so read the triggers carefully.
What’s Legally Required vs. Recommended
It helps to separate what the law forces you to carry from what’s merely smart business — though in practice, the “recommended” items are often required by the venues you work with.
| Coverage | Status | Notes |
|---|---|---|
| Commercial Auto | Verify vehicle requirements | Check jurisdiction, vehicle type and use |
| Workers’ Compensation | Verify employment requirements | Check staffing thresholds, structure and exemptions |
| General Liability | Recommended / Often required | Demanded by most events, markets, and landlords |
| Product Liability | Strongly recommended | Critical for any food business; sometimes required |
| Property / Equipment | Recommended | Often required if your truck is financed |
| Business Interruption | Optional | Valuable for seasonal or single-location operators |
If your truck is financed or leased, the lender will almost certainly require physical-damage (collision/comprehensive) coverage as a condition of the loan, regardless of what your state mandates.
Budget After You Choose the Coverage
Price comparisons only make sense when every quote uses the same vehicles, drivers, limits, deductibles, endorsements, and covered equipment. Build that coverage specification first, then compare premiums and payment schedules in the food truck insurance cost guide. Model the resulting recurring expense in the profit calculator.
Additional Insured and Event Requirements
Collect each venue’s legal name, limits, and additional-insured wording, then ask the broker which endorsement is needed. A certificate summarizes coverage; it does not itself add the venue or change policy terms. Confirm charges and processing time before the event.
Build a little lead time into your event calendar: requesting and receiving a COI naming a specific venue can take a day or two, and showing up without the right paperwork can mean being turned away at the gate. Keep a digital copy of your current COI handy and confirm each host’s exact requirements well before the event date.
Check the jurisdiction and the contract
Confirm vehicle coverage rules with the relevant state agency and employment coverage rules with the workers’ compensation authority. Requirements can depend on business structure, staffing and exemptions. In NYC, the mobile-vending application asks for workers’ compensation and disability evidence or an eligible CE-200 exemption; see the NYC permit guide. That does not establish universal $2 million GL or $1 million auto statutory minimums.
Collect site, event, lender and commissary terms separately. An additional-insured requirement or a contractual limit is not automatically a law applying to every operator. Distinguish per-occurrence limits from aggregate limits and ask the broker to show how the proposed coverage satisfies each document.
How to Get Food Truck Insurance Quotes
Prepare a consistent coverage specification before requesting quotes so you can compare limits, deductibles, exclusions, and payment terms:
What you’ll need before calling brokers
- Your truck’s year, make, model, and VIN
- Estimated annual mileage and operating radius
- Menu type (determines fire/liability risk tier)
- Number of employees and approximate annual payroll
- List of events or venues you plan to work (some require additional insured certificates)
- Your driving history (past 3–5 years)
- Whether the truck is financed (lender requirements)
Where to get quotes
- Mobile-food insurance providers and independent brokers can help compare the relevant coverage. Verify what each program includes; FLIP explicitly excludes commercial auto from its advertised program
- State farm bureaus and local independent agents can bundle with your personal auto and home for multi-policy discounts
- Your commissary’s recommended carrier — some commissaries negotiate group rates for their members
Questions to ask every carrier
- Does the GL policy include product liability, or is it a separate line?
- Is the cooking equipment covered in transit under commercial auto or property?
- What’s the claims process if I have a health department shutdown?
- Do you offer blanket additional-insured coverage or must I list each venue separately?
- What triggers business interruption — does it cover health code violations?
Compare multiple written proposals against the same requirements. A lower premium may come with different coverage or deductibles.
Claims Scenarios and How Insurance Responds
Understanding when your policy actually pays out helps you avoid coverage gaps:
A customer slips on a wet spot near your truck. → General liability may respond to third-party bodily injury, subject to the policy, facts, limits and exclusions. A sample limit cannot predict the claim outcome.
Your generator fails at a weekend festival and you lose a full refrigeration load of product. → Ask whether equipment breakdown and spoilage are covered; ordinary property coverage may exclude mechanical failure. Business interruption may also cover lost revenue from that weekend if the failure is covered under the policy’s trigger.
A customer reports a foodborne illness and files a claim. → Product liability may respond subject to policy terms and claim facts. Ask whether defense costs are covered, how they affect limits, and which policy handles the claim.
You rear-end another vehicle while driving to an event. → Commercial auto liability and selected collision coverage may respond, subject to terms and deductibles. Do not assume a personal policy covers the commercial use.
An employee cuts their hand badly on kitchen equipment. → Workers’ compensation may cover medical care and wage benefits under the applicable rules. Confirm reporting duties and coverage with the carrier; this example does not determine legal liability.
Your truck is totaled in a fire while parked at the commissary. → Confirm which physical-damage and property coverages apply to the vehicle, equipment and stock, including exclusions and deductibles. If you’re financing the truck, the lender is typically the first payee.
Frequently Asked Questions
Does my food truck need insurance before I can get a permit? Requirements vary. Some permitting authorities require specific insurance evidence, while others separate insurance from the health-permit process. Events, commissaries, property owners, and lenders can impose their own requirements. Confirm each one before applying or signing a contract.
What insurance is legally required for a food truck? Commercial auto and workers’ compensation requirements depend on the vehicle, state, business structure, and staffing. General or product liability may also be required by a permit, venue, commissary, landlord, lender, or client even when it is not a statewide statutory requirement. Verify the rules that apply to your operation.
Is commercial auto the same as personal auto insurance? No. Personal auto policies commonly exclude or limit business use. Disclose the vehicle’s commercial use and confirm the required commercial auto coverage with a licensed agent or carrier.
Do I need product liability if I already have general liability? Product liability may be included in a general liability or package policy, but policy forms differ. Confirm that foodborne illness, contamination, and allergic-reaction claims are covered and review any exclusions.
What’s the difference between a food truck BOP and a food truck package policy? A BOP bundles GL and commercial property. Other package programs may add policies or endorsements, but auto and workers’ compensation are not automatically included. Ask for an itemized coverage proposal; bundling has no guaranteed percentage saving.
How do I add a venue as additional insured? Call or email your broker with the venue’s legal name and address. Confirm the required endorsement, any charge and the processing time. Obtain the endorsement and the appropriate certificate before the event; a certificate alone does not change policy terms.
Related Guides
- Food Truck Insurance Costs — annual and monthly premium planning
- Food Trailer Insurance Cost — coverage and cost differences for a towable rig
- Food Truck Permit Costs — permit categories and local verification steps
- Startup Cost Calculator — compare fixed setup allowances; record broker quotes in your own budget
Methodology & Assumptions
Cost ranges are planning models assembled from the line items and assumptions shown in this guide. They are not quotes or guaranteed market averages. This page identifies 4 cited sources; official fees and requirements should be checked against those links. AI tools may assist with organization and drafting, but they are not a source and no independent food-truck operator review is claimed. Local rules and prices can change; verify them before committing funds. Last updated: 2026-11-10.
Sources & verification
- Insureon — Food truck insurance costs Verified 2026-11-08; page updated 2026-09-18. Customer-policy examples; commercial auto includes food service businesses; not additive totals.
- FLIP — Food truck insurance Verified 2026-11-08: advertised starting prices; explicitly not a commercial auto policy.
- U.S. Small Business Administration — Get business insurance Official overview of common business coverage types and risk-based purchasing.
- National Association of Insurance Commissioners — Business insurance Consumer guidance from U.S. state insurance regulators; actual premiums require carrier quotes.
Regulations and fees change. Confirm the current application, fee schedule, and operating rules with the issuing agency before purchasing a vehicle or signing a commissary agreement.